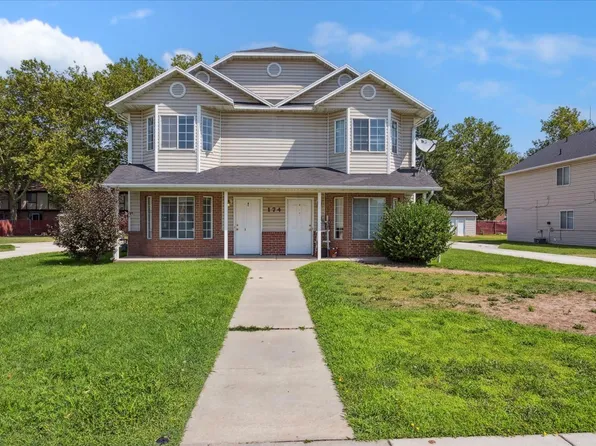
Buy a duplex, triplex, or fourplex with a VA loan? Yep. Here’s how occupancy, rental income, reserves, and zero-down financing actually work.
Yes.
And this is one of the most overlooked benefits of the VA loan.
An eligible Veteran or service member can use a VA-backed purchase loan to buy a property with up to four units.
That means you could potentially buy:
A duplex.
A triplex.
A fourplex.
Live in one unit and rent out the others.
But there’s one pretty damn important rule:
You have to actually live there.
A VA loan is a benefit designed to help you purchase a primary residence. It is not a program for buying a fourplex that you never intend to occupy.
That distinction matters.
You Have to Occupy One of the Units
Buying a four-unit property does not mean all four units have to be occupied by you and your family.
You only need to occupy one unit as your primary residence.
VA guidance generally considers moving into the property within 60 days after closing a reasonable occupancy period, although certain circumstances can allow additional time.
So, yes:
You can live in Unit A.
Your tenants can live in Units B, C and D.
That's completely different from buying a traditional investment property where you never intend to live.
Can Rental Income Help You Qualify?
Potentially.
This is where these transactions get more interesting — and also where you need a loan officer who actually understands VA underwriting.
VA underwriting guidance allows prospective rental income from the additional units to be considered in qualifying when certain requirements are met.
The VA handbook says the borrower must demonstrate a reasonable likelihood of success as a landlord and have sufficient reserves. When qualifying rental income is used, VA guidance generally uses 75% of the lease amount or qualifying appraiser-supported market rent, depending on the situation.
In plain English:
If another unit could rent for $2,000 per month, don't automatically assume your lender is going to give you $2,000 of additional qualifying income.
The underwriting calculation matters.
What About Cash Reserves?
This is another place people get surprised.
For a multi-unit property securing the VA loan, when prospective rental income is being used, VA underwriting guidance calls for at least six months of PITI reserves and documentation supporting the borrower's ability to successfully manage rental units or use a property-management company.
PITI means:
Principal + Interest + Taxes + Insurance.
And no, equity in the property isn't the same thing as having those reserves sitting there. VA guidance specifically says equity can't be used to satisfy this reserve requirement.
This is why I keep saying:
Getting a VA loan isn't just about whether something is technically allowed. It's about structuring the damn loan correctly.
Do You Need a Down Payment?
Not necessarily.
VA states that VA-backed purchase loans often allow eligible borrowers to purchase with no down payment, provided the sales price doesn't exceed the appraised value and the borrower otherwise qualifies.
But your specific situation still matters.
Your VA entitlement matters.
The purchase price matters.
Your income and debts matter.
The VA appraisal matters
And if you have previously used some of your VA entitlement, the calculation can change. VA instructs lenders to use the one-unit conforming loan limit when determining remaining bonus entitlement, even when the property itself has multiple units.
So don't look at a fourplex price online and assume, “VA means zero down.”
Run the actual numbers.
Why Would a Veteran Consider Doing This?
Because instead of simply buying a house, you may be able to buy a home that also produces rental income.
You live in one unit.
Other people pay rent in the others.
That rental income may help offset some of the cost of owning the property.
And you're using a home-loan benefit you earned to do it.
I'm not saying everybody should run out and become a landlord.
I'm saying most Veterans don't even know this option exists.
That's a problem.
Is a VA Multi-Unit Purchase an Investment Property?
Here's the important distinction.
The additional units can generate rental income, but you still have to purchase the property intending to use one unit as your home.
VA's occupancy requirement is clear: the Veteran obtaining the VA-guaranteed loan must certify an intent to personally occupy the property as a home.
So:
Fourplex where you live in one unit? Potentially yes.
Fourplex you're buying solely to rent all four units? That's not what a VA purchase loan is for.
Pretty simple.
The Bottom Line
Yes, you can potentially buy a duplex, triplex or fourplex with a VA loan.
You can live in one unit.
You can rent the others.
Qualifying rental income may be considered.
And depending on your eligibility, entitlement, appraisal and overall qualification, a VA-backed purchase loan may allow you to do it without a traditional down payment.
But multi-unit VA loans have additional underwriting considerations that a normal single-family purchase doesn't.
If you’re still learning how the VA loan works, start with my complete VA loan guide here.
This isn't the loan where you want somebody learning VA guidelines while they're working on your file.
If you're considering buying a multi-unit property with your VA benefit, run the numbers before you start making offers.